
Crypto Taxes Explained: Rates & Rules (2026)
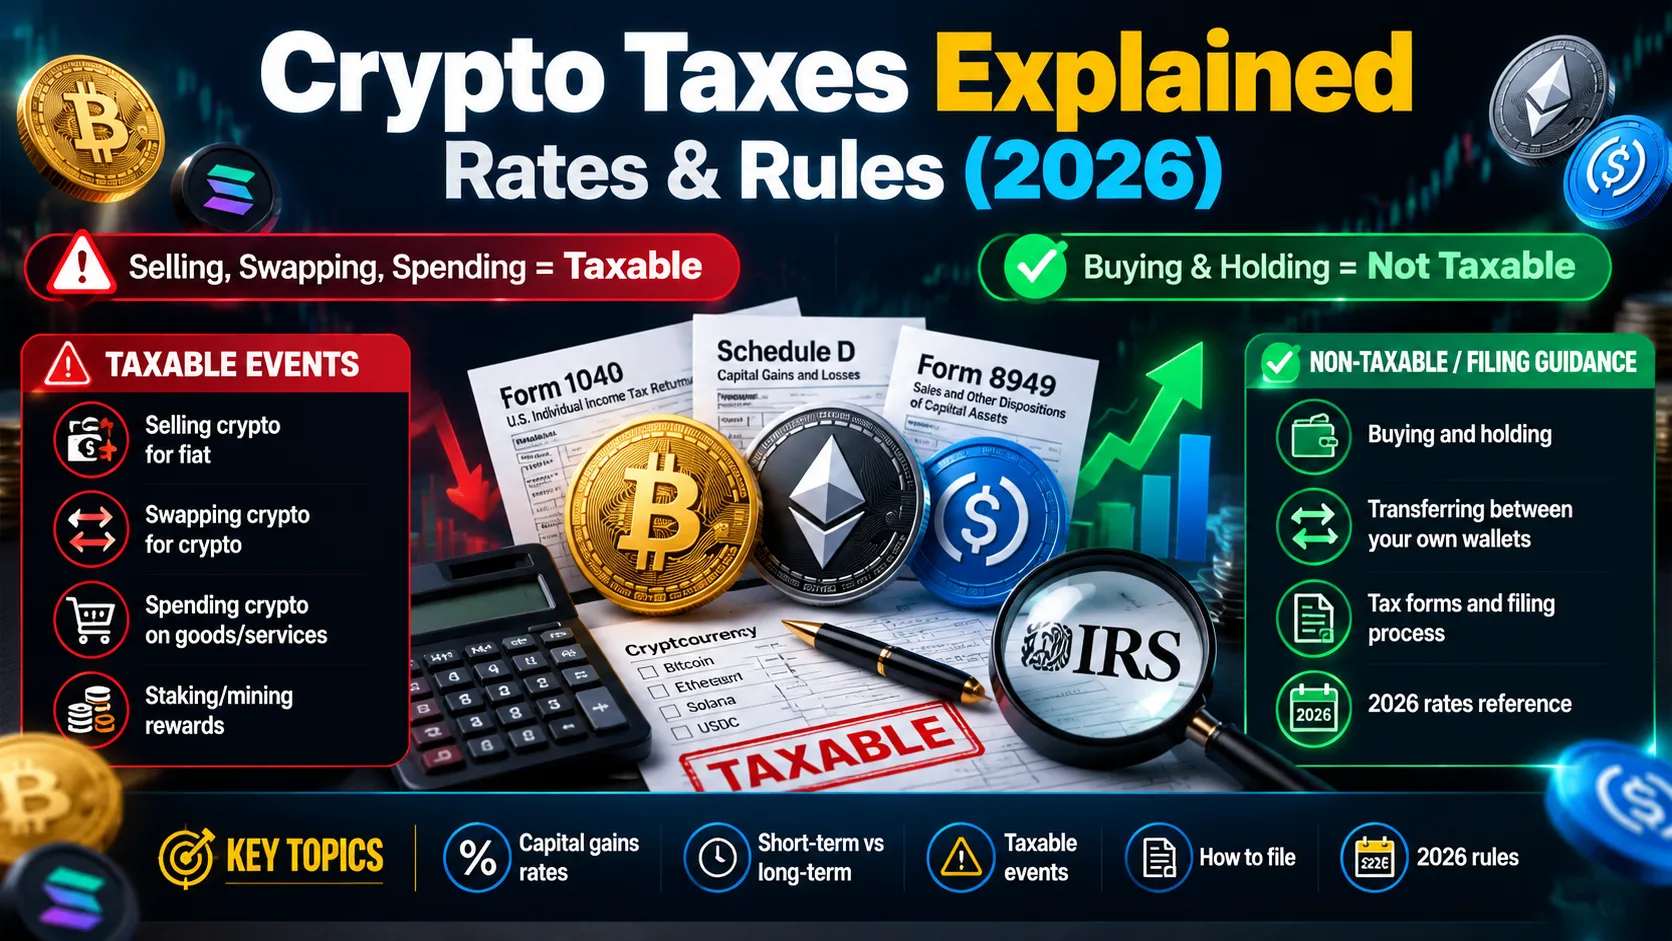
Selling, swapping, or spending crypto is a taxable event; buying and holding is not. How US crypto taxes work in 2026: rates, rules, and how to file.
 Lucas Almeida 5 min read
Key takeaways
- In the US, the IRS treats crypto as property: selling, swapping one coin for another, or spending it is a taxable disposal — but buying, holding, and moving coins between your own wallets are not (IRS Notice 2014-21).
- Hold for more than a year and gains are taxed at long-term rates of 0%, 15%, or 20% in 2026; sell within a year and they are taxed like salary at your normal income rate, which runs from 10% to 37%.
- Staking rewards, mining income, and most airdrops are ordinary income at the coin's market value on the day you receive it.
- Starting with the 2025 tax year, US exchanges issue Form 1099-DA — but a missing form does not mean no tax: the IRS requires every gain and loss to be reported regardless of amount.
- The single biggest legal lever is time: the difference between short-term and long-term treatment is often the difference between your full income tax rate and 15% — and losses can offset gains dollar for dollar.
The direct answer: in the US, yes — the IRS taxes cryptocurrency as property, so selling it, swapping it for another coin, or spending it can trigger capital gains tax, while simply buying it and holding it does not. For 2026, most long-term gains are taxed at 0%, 15%, or 20%, and short-term gains are taxed like salary. You do not owe tax just because the price moved.
That one paragraph is the whole skeleton. Everything else — rates, forms, record-keeping — hangs off a single distinction: tax happens when you dispose of a coin, not when you own it. This guide walks through what counts as a taxable event, what the rates actually are for 2026, what your exchange now reports to the IRS, and the small number of legal levers that genuinely reduce the bill. It focuses on US federal rules because that is where most readers ask from; other countries are covered in a short section near the end. This is general education, not tax advice — for anything beyond a simple buy-and-sell, a professional who knows crypto should check your specific situation.
Which Crypto Moves Trigger a Taxable Event?
The taxable ones are the moves where you give up a coin: selling it for dollars, swapping it for a different cryptocurrency, or paying someone with it. Every other move — buying, holding, receiving it as a gift, transferring it between your own accounts — does not create a tax bill.
The IRS is explicit about this in its FAQ on virtual currency transactions (last updated under its current digital asset guidance): exchanging virtual currency “for other property, including for goods or for another virtual currency” recognizes a capital gain or loss. Here is the practical version as a table:
| Move | Taxable? | Why |
|---|---|---|
| Buy crypto with dollars | No | You are acquiring, not disposing |
| Hold while the price moves | No | Unrealized gains are not taxed |
| Sell crypto for dollars | Yes | Disposal — gain or loss vs. what you paid |
| Swap BTC for ETH (or any coin for another) | Yes | Disposal — treated as a sale, even though no dollars appeared |
| Spend crypto on goods or services | Yes | Disposal — the “price” you received is the value of what you got |
| Transfer between your own wallets/exchanges | No | Explicitly non-taxable under IRS guidance |
| Receive crypto as a genuine gift | No (not yet) | You inherit the donor’s basis; tax comes when you dispose |
| Get paid in crypto for work | Yes | Ordinary income at market value on receipt |
| Earn staking/mining rewards | Yes | Ordinary income at market value on receipt |
| Receive an airdrop | Usually Yes | Ordinary income when you can control the coins |
The row that surprises beginners most is the swap one. If you trade 1 BTC for 15 ETH on an exchange, no dollars ever touched your bank account — and there is still a taxable event, because the IRS treats it as selling your Bitcoin. The gain or loss is measured in US dollars, not in coins.
How Does the IRS Tax Crypto Exactly?
Crypto is taxed as property, the same category as stocks or a rental house — not as currency. That rule comes from IRS Notice 2014-21 and still governs everything.
Property treatment produces a simple formula for every disposal:
Gain or loss = what you sold it for − what it cost you (your “basis”)
Your basis is what you paid, including fees — the exchange commission, the network fee at purchase, and other acquisition costs count toward it (IRS FAQ, A8). Sell at $7,800 something you bought for $6,000, and you have a $1,800 gain. Sell at $4,500, and you have a $1,500 loss — and losses matter just as much as gains, as we’ll see.
How the gain is taxed depends on one thing: how long you held the coin before disposing of it (IRS FAQ, A6):
- Short-term — held one year or less: the gain is added to your ordinary income and taxed at your normal income tax rate.
- Long-term — held more than one year: the gain is taxed at the preferential capital gains rates below.
The clock starts the day after you acquire the coin and ends the day you dispose of it. This is why the boring advice — don’t sell in a panic after three months — has a direct dollar value: the same dollar of profit can be taxed at 32% or at 15% depending entirely on the calendar.
What Are the Crypto Tax Rates for 2026?
For 2026, short-term gains are taxed at your ordinary income rate — the same seven brackets (10% up to 37%, per IRS Revenue Procedure 2025-32) that apply to your salary. Long-term gains get their own, much friendlier table, based on your total taxable income, not just the crypto profit:
| Long-term rate | Single filers (2026) | Married filing jointly (2026) |
|---|---|---|
| 0% | taxable income up to $49,450 | up to $98,900 |
| 15% | $49,451 – $545,500 | $98,901 – $613,700 |
| 20% | above $545,500 | above $613,700 |
(Thresholds from IRS Revenue Procedure 2025-32, as published by the Tax Foundation and NerdWallet.)
Three details people miss:
- The 0% bracket is real. A student or lower-income earner who sells coins held over a year may genuinely owe nothing on the gain — because the rate applies to your total taxable income, not the size of the crypto win.
- High earners pay one more layer. The 3.8% Net Investment Income Tax (NIIT) applies to investment gains once your modified adjusted gross income exceeds $200,000 single / $250,000 married — a statutory threshold that doesn’t adjust for inflation.
- State taxes come on top. Most US states tax capital gains as ordinary income; a handful (like Texas and Florida) don’t. The tables above are federal only.
What Would You Actually Owe? Two Examples
Abstract rates are forgettable, so here are two concrete trades — one short-term, one long-term — worked all the way through.
Example 1: the quick flip. You buy 0.1 BTC for $6,000 (including the $8 exchange fee) in March 2026. In November 2026, eight months later, you sell it all for $7,800. Holding period: under a year, so this is a short-term gain of $1,800, which is added on top of your other income and taxed at your normal bracket. If your top bracket is 22%, the tax on this trade is about $396.
Example 2: the patient hold. You buy $1,000 of ETH in January 2025. In August 2026 — nineteen months later — it has grown to $2,500 and you sell. That is a long-term gain of $1,500, and now your total income decides the rate:
- Total taxable income $40,000 (single) → inside the 0% bracket → tax owed: $0
- Total taxable income $95,000 (single) → 15% bracket → tax owed: $225
- Total taxable income $700,000 (single) → 20% bracket + 3.8% NIIT → tax owed: about $357
Same $1,500 of profit. In the middle scenario, waiting nineteen months instead of selling at month eight saved roughly $100–$250 in tax compared to a 22–24% short-term rate — and the gap widens as income rises. Note one nuance: holding longer does not always win. If an asset is collapsing, a smaller short-term loss you can harvest may beat a bigger long-term one. The rate table rewards patience only when the position is actually worth more.
Does Your Exchange Report Taxes for You Now?
Since the 2025 tax year, yes — mostly. US brokers now issue Form 1099-DA, “Digital Asset Proceeds From Broker Transactions,” for sales they effect for customers, and send a copy to the IRS. It is the crypto equivalent of the 1099-B stock investors have received for years, and it first applied to transactions on or after January 1, 2025.
But “the exchange reports” is not the same as “the exchange handles it,” and this is the part worth reading twice:
- The form shows gross proceeds, not necessarily your gain. Basis reporting is still phasing in — coins you bought before 2025, on another platform, or transferred in are often reported as “noncovered,” meaning the form shows the sale price but may be blank or unreliable on what you paid. The gain you compute yourself from your own records is the number that counts.
- Transfers create phantom proceeds. When you move coins from Exchange A to your own wallet, some platforms’ records treat the move as a “disposition” — statements can show large proceeds with no visible purchase behind them. Under IRS guidance this transfer is explicitly not taxable (FAQ A38: a transfer between wallets or accounts belonging to you is a non-taxable event). But if you just forward the exchange’s numbers to your tax return, you can accidentally report income that doesn’t exist. This is the single most common crypto tax scare we see beginners hit, and it is entirely a paperwork problem, not a tax problem.
- Small sales may not generate a form. The 2025 instructions include a de minimis reporting minimum — around $600 in gross proceeds — below which a broker may not file for you. The IRS is explicit that this changes nothing on your side: every gain and loss is reportable “regardless of the amount or whether you receive a payee statement” (FAQ A42).
- No form was ever an alibi, and now it isn’t even plausible. Before 2025, “I didn’t get any tax forms” was a common (and unconvincing) excuse. With 1099-DA in its second year, the IRS matches broker reports against returns automatically. Discrepancies generate CP2000 notices with interest and potential penalties attached.
If you haven’t chosen an exchange yet, this is one quiet reason to pick a large, established one: they are the platforms whose reporting matches the new forms cleanly, and their transaction exports actually reconcile when tax season comes.
💡 Don't have a Binance account yet? Sign up now — 20% fee rebate on spot and futures — enter the referral code BN2688.
What About Staking, Mining, and Airdrops?
Rewards you earn are taxed as ordinary income at the coin’s market value on the day you receive it — before you ever sell. That is a different bucket from capital gains, and it applies at the moment of receipt, not at the moment of disposal.
- Staking rewards are income when you gain control of them — the IRS settled this in Revenue Ruling 2023-14. If you earn 0.05 ETH worth $150 on the day it lands, you have $150 of ordinary income, and that $150 becomes your basis for later.
- Mining income works the same way, taxed as ordinary income at fair market value on receipt (and as self-employment income if mining is a business, per IRS FAQ A10).
- Airdrops are income when you can actually control the coins — Revenue Ruling 2019-24 covers hard forks and airdrops. A token you receive with no ability to sell or move it isn’t yet income; the moment you can dispose of it, it is.
The part beginners miss: many people are taxed twice in a chain they don’t notice. The $150 staking reward is income on day one, and when you eventually sell that ETH, the sale itself is a capital gain or loss measured from the $150 basis. Neither step is optional, but they are also not double taxation — the basis you declared as income comes back out of the sale calculation.
How Do You Report Crypto on Your Tax Return?
Reporting happens through the standard capital gains pipeline: Form 1040’s digital asset question, then Form 8949, then Schedule D. Every US filer answers the digital asset question on Form 1040 each year — answering it falsely is its own problem, even if your total activity is tiny.
The mechanics, in order:
- List every disposal on Form 8949 — date acquired, date sold, proceeds, basis, gain or loss. One line per sale or per lot.
- Totals flow to Schedule D, which nets your short-term and long-term gains and losses.
- Attach the math to your 1040 and answer the digital asset question honestly.
Underneath the forms sits the thing that actually decides how painful this is: your records. The IRS requires you to substantiate basis and dates (FAQ A46), and exchanges only keep clean data for their own platform. Before January rolls around, make sure you can produce, for every transaction:
| What to record | Why it matters |
|---|---|
| Date and time of each buy/sell | Decides short- vs. long-term treatment |
| Amount of coin and its USD value at the time | Fixes proceeds and basis in dollars |
| Fees paid on each side | Fees reduce your gain (or shrink your loss) |
| Where coins moved and why | Proves self-wallet transfers aren’t sales |
| Transaction ID or exchange export | Your evidence if numbers are ever questioned |
For 2026 activity, the filing deadline is April 15, 2027 (October 15, 2027 with an extension). One more deadline trap: if your crypto activity means you’ll owe $1,000 or more at filing, the US expects quarterly estimated tax payments during the year, not one lump sum in April — under-withholding can add underpayment penalties on top of the tax itself.
How Can You Legally Lower the Bill?
Four levers do almost all of the work, and none of them involve anything exotic:
- Hold past one year. This is 80% of the game. The same profit taxed at your 22–32% bracket short-term becomes 15% (or 0%) long-term. If you have no immediate need to sell and the position is sound, the calendar is worth real money.
- Harvest your losses. Selling a coin that’s down cancels gains elsewhere in your portfolio dollar for dollar; beyond that, up to $3,000 a year of net loss can offset ordinary income, and the rest carries forward. And here crypto has a genuine edge over stocks: the wash-sale rule — which blocks stock investors from selling at a loss and rebuying immediately — applies to “stock or securities,” and digital assets are not covered as of 2026. Selling a losing coin and buying it back right away to lock in the loss currently works. Two cautions: Congress has repeatedly floated closing this gap, so verify the rule is still current before relying on it, and don’t harvest losses purely to churn fees.
- Choose which lots you sell. If you bought the same coin at several prices, you can specifically identify which lot you’re selling — pointing at your highest-cost lots shrinks the reported gain (IRS FAQ A39–41 supports specific identification with adequate records). Without documentation, the default is FIFO: first coins in are treated as first sold.
- Donate appreciated coins directly to a qualified charity if you give anyway: you generally deduct the fair market value for coins held over a year, and you never realize the gain (IRS FAQ A34–35).
What you should not do is anything premised on the exchange not knowing: P2P trades, self-custody swaps, and DeFi trades are all reportable disposals exactly the same as on-exchange sales. The blockchain remembers what your brokerage statements never could.
What If You Didn’t Report Past Crypto?
Fix it forward, quietly and correctly. If you missed reporting crypto in earlier years, the standard path is filing amended returns for the open years — typically the last three to six, depending on the size of the error — reporting the activity properly and paying the tax plus interest. Interest and most penalties accumulate with time, which is precisely why correcting voluntarily before the IRS contacts you is categorically better than waiting for a CP2000 that now, post-1099-DA, has your broker’s numbers attached.
The honest bottom line for small amounts: if you bought, never sold, and only owe on a couple of small trades, the fix is usually cheap and mechanical. If the activity involves years of swaps, DeFi, or missing basis data, pay a crypto-literate tax professional for an hour before filing anything. That hour costs less than one penalty cycle.
How Do Crypto Taxes Work Outside the US?
The property-style “sell means tax” logic is common, but the rates and holding-period rules differ enough that copying US advice abroad can cost you money. Rough orientation, current as of late 2026 — always confirm against your national authority, since these rules change:
| Country | Basic treatment |
|---|---|
| United Kingdom | Gains above the annual exempt amount (£3,000 for 2025/26) are taxed as capital gains; rates depend on your income band. HMRC’s cryptoassets manual is the authoritative source. |
| Germany | The friendliest large market: private sales of crypto held more than one year are tax-free, and small yearly sale volumes under €1,000 are exempt — a genuinely different philosophy from the US. |
| Australia | Crypto is subject to capital gains tax, but holding over 12 months earns a 50% discount on the gain. The ATO’s crypto guidance covers swaps, staking, and airdrops. |
| Canada | Crypto dispositions are taxed as income with only half of each gain included in taxable income. The CRA expects self-reporting of every disposal, including crypto-to-crypto trades. |
Germany is the outlier worth knowing about: its one-year rule means the single most valuable US strategy — hold past twelve months — is even more valuable there, since the reward is zero tax rather than a 15% rate. Conversely, some countries tax every gain at full income rates with no holding-period benefit at all, which inverts the logic entirely.
The Bottom Line
Crypto taxes are simpler than the fear around them suggests: you are taxed when you dispose of a coin — selling, swapping, or spending — and the rate depends almost entirely on how long you held. Buy and hold all you like; the IRS doesn’t care until you let go. In 2026 the long-term rates are 0%, 15%, and 20%, short-term gains ride on your salary bracket, and since 2025 your exchange sends a Form 1099-DA to both you and the IRS.
If you’re just getting started, three habits prevent almost every future problem: keep a dated record of every transaction from day one, prefer holding past twelve months when the position is sound, and set aside a slice of any large gain for estimated taxes as you go. When you do sell — or if you want to see what a full sell-and-withdraw flow looks like end to end — our guide to selling crypto and withdrawing to your bank picks up exactly where this one ends.
Don't have a Binance account yet?Sign up nowenter the referral codeBN2688
Frequently asked questions
Do I owe crypto tax if I bought but never sold?
Is transferring crypto between my own wallets taxable?
How does the IRS know about my crypto?
Is swapping Bitcoin for Ethereum taxable?
What crypto profit is tax-free in the US?
Do I pay tax twice when I spend crypto on something?
Editor-in-Chief & Lead Researcher
Editor of MyCryptoStart. Independent researcher of cryptocurrency exchanges, focused on fees, security, KYC, and onboarding — publishes step-by-step guides in plain English for beginners.
View author page →Some links on this page are affiliate links: we may earn a commission at no extra cost to you. This content is educational and is not financial, investment, or legal advice. Affiliate disclosure · Disclaimer.
Continue reading
What Is a Crypto Airdrop? How It Works (2026)
A crypto airdrop sends free tokens to eligible wallets, usually for past activity. How snapshots, claims, taxes and airdrop scams actually work in 2026.
How to Stake Crypto and Earn Yield (2026)
Crypto staking locks your coins to secure a proof-of-stake network and earn rewards — typically 2–8% a year. Learn how it works, the real risks, and how to start.
Dollar-Cost Averaging (DCA) in Crypto (2026)
Dollar-cost averaging buys a fixed dollar amount of crypto on a set schedule. Learn how DCA works, what backtests show, and when lump sum wins.