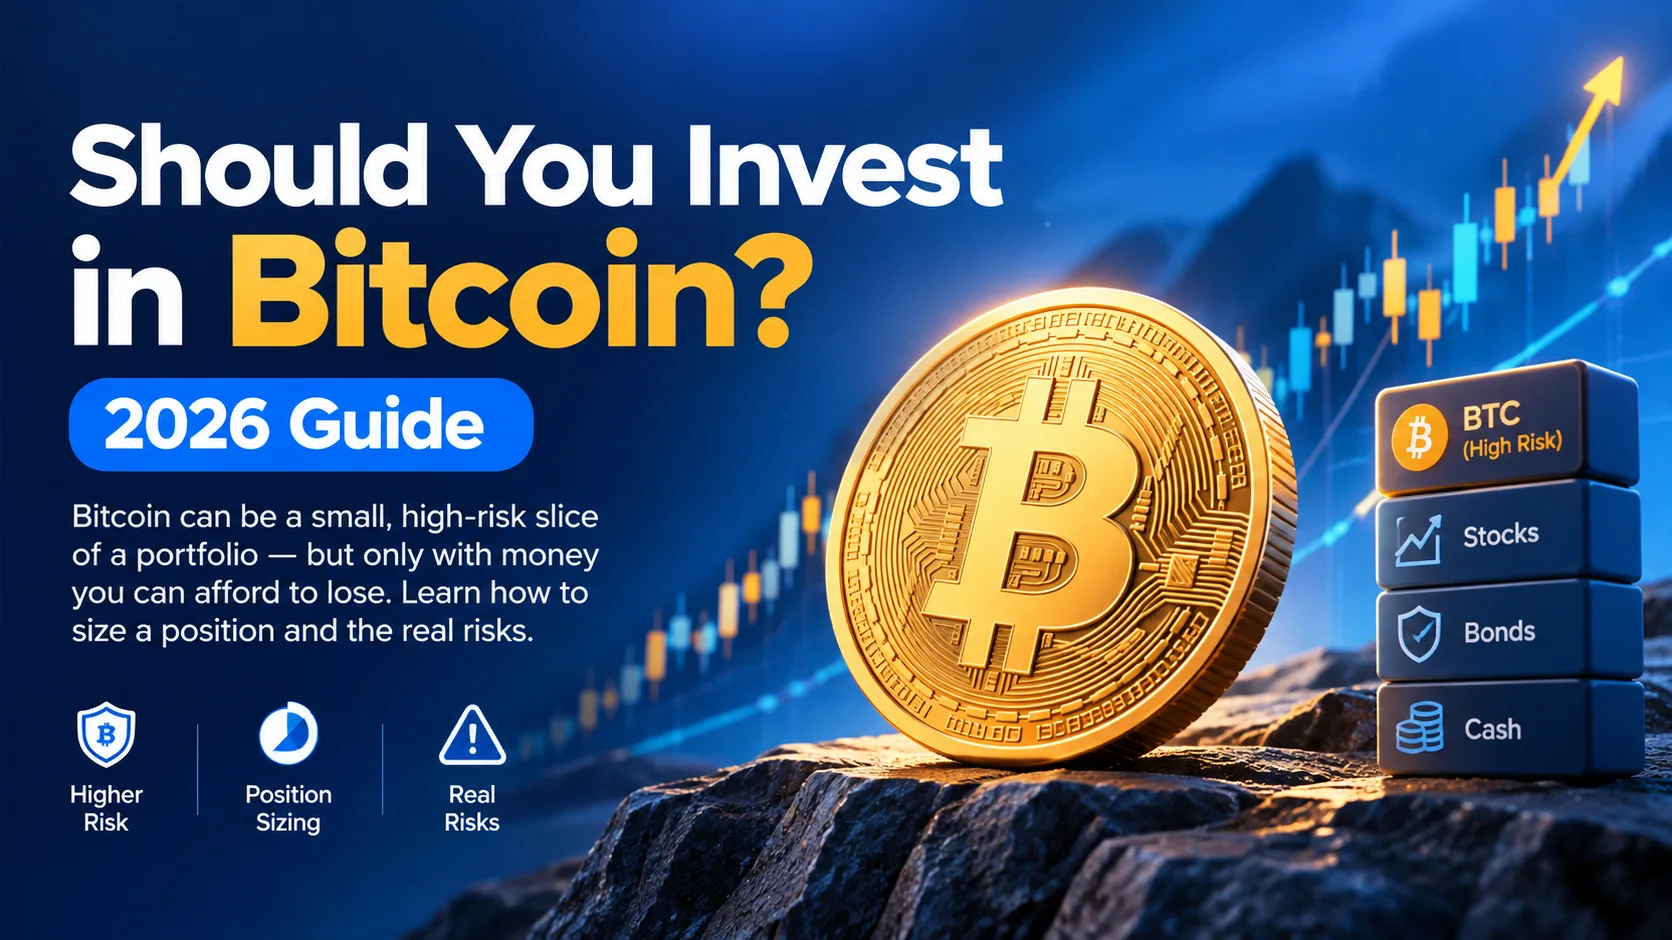
Should You Invest in Bitcoin? (2026 Guide)
Bitcoin can be a small, high-risk slice of a portfolio — but only with money you can afford to lose. Learn how to size a position and the real risks.
 Lucas Almeida 5 min read
Key takeaways
- No one can promise Bitcoin will go up. The honest answer to "should I invest?" is a conditional yes: a small position you could lose entirely, held for years, not a bet on short-term price.
- Sizing matters more than timing. BlackRock's own research caps Bitcoin at 1–2% of a portfolio, because even a 2% allocation carries about as much risk as a single mega-cap tech stock.
- Bitcoin peaked near US$126,000 in October 2025 and has traded roughly a third below that through late 2026 — after falling 70–80% from its highs more than once.
- There are two ways to buy: directly on an exchange (you hold the coins and the keys) or through a spot Bitcoin ETF in a normal brokerage account (no keys, roughly 0.25–0.40% annual fee).
- Dollar-cost averaging — a fixed amount on a fixed schedule — beats trying to time the market, and the only money that belongs in Bitcoin is money whose total loss wouldn't change your life.
For most beginners, the honest answer is a qualified yes — but only as a small, long-term position you could lose entirely without it changing your life. Bitcoin has been one of the best-performing assets of the past fifteen years and one of the most volatile, often in the same year. Whether it’s right for you depends less on “is Bitcoin good?” and more on three things you control: how much you put in, how long you can leave it alone, and whether you could watch it fall 70% without panic-selling.
This guide walks through each of those. It’s education, not financial advice — and anyone who gives you a confident, one-word answer to this question is the person you should be most careful around.
What does “investing in Bitcoin” actually mean?
Buying Bitcoin is not like buying a stock: you’re not buying a share of a company’s future earnings — you’re buying a scarce digital asset whose price is set only by what someone else will pay later.
That distinction is the whole game. A share of a company entitles you to its profits, paid out as dividends or buybacks. Bitcoin produces no earnings, pays no dividend, and throws off no cash flow. Its value rests on three properties: a hard cap of 21 million coins (about 19.9 million already exist), its usefulness for moving value across borders without a bank, and the collective belief of the people and institutions holding it. We explain the mechanics in our Bitcoin guide and blockchain guide; the investment-relevant point here is narrower: you’re betting the price will be higher later, and nothing structural guarantees it will be.
That’s why “investing” in Bitcoin is more like buying a volatile, uncorrelated commodity — digital gold, in the common shorthand — than like building a retirement portfolio out of cash-flowing assets. It can earn a place in a portfolio, but only as a small satellite, not as the core.
Why do people invest in Bitcoin?
The case for Bitcoin comes down to scarcity, adoption, and a track record that — over full cycles — has rewarded patience.
The concrete arguments, in plain terms:
- Scarcity is enforced by code. Only 21 million bitcoins will ever exist, and the rate of new supply is cut in half roughly every four years. No committee can print more, which is the property people compare to gold.
- Institutional adoption is real. In January 2024, US regulators approved the first spot Bitcoin ETFs, letting ordinary brokerage accounts hold Bitcoin the way they hold stocks. That market passed roughly US$86–128 billion in assets during 2026, with BlackRock’s iShares Bitcoin Trust (IBIT) alone holding close to 800,000 BTC at one point.
- Governments and large investors now hold it. The US established a Strategic Bitcoin Reserve in March 2025, formally treating Bitcoin as a reserve asset — something unthinkable a decade earlier.
- The long-run numbers are striking. By several counts, Bitcoin has been the world’s best-performing asset in 10 of the past 13 years — and among the worst in the other three.
That last point is not a throwaway. The same asset that tops the performance charts most years also posts some of the deepest losses. Anyone telling you only half of that story is selling you the half they want you to believe.
What are the real risks?
Bitcoin’s risks are not a footnote — they’re the reason position sizing and time horizon matter more than any price prediction.
- Extreme volatility. Bitcoin’s annualized volatility runs around 65%, and it has dropped 70–80% from its highs more than once (2014, 2018, 2022). It peaked near US$126,000 in October 2025 and traded roughly a third below that through late 2026. A third of your money evaporating in under a year is not a hypothetical — it’s the recent record.
- No cash flow, no floor. Because Bitcoin earns nothing, there’s no dividend yield or book value to catch the price when sentiment turns. The bottom is set purely by where the next buyer is willing to step in.
- Behavioral risk — the one that costs people the most. The typical losing pattern isn’t “Bitcoin went to zero.” It’s buying near a euphoric top and panic-selling near the bottom, locking in the loss. One 2026 analysis put it in plain numbers: $1,000 invested at the October 2025 peak was worth about $600 by September — a loss that only became real for the people who sold.
- Platform and custody risk. Exchanges can fail or be robbed. The FTX collapse in 2022 erased billions in customer funds, and Chainalysis counted US$2.2 billion stolen in crypto hacks in 2024 alone. A mistake with your own keys is equally permanent — there is no “reset password.”
- Regulatory risk. Most large economies permit Bitcoin under licensing and tax rules, but those rules can tighten, and in most places selling or spending Bitcoin is a taxable event you’re responsible for recording. For the current landscape, Morningstar’s 2026 guide to Bitcoin is a clear, source-backed read.
None of these mean “don’t invest.” They mean: invest small, invest with money you can lose, and secure what you buy. We cover the fraud and security side in depth in our crypto scams guide and wallet security guide.
How much should a beginner invest?
The only number that has a real research basis is small — and the most useful framework comes from the world’s largest asset manager.
BlackRock’s investment institute, in its paper Sizing Bitcoin in Portfolios, recommends 1–2% for a multi-asset portfolio. The reasoning is the useful part: Bitcoin’s volatility is so high that even a small slice contributes an outsized share of your total risk.
| Bitcoin allocation | Share of total portfolio risk it contributes |
|---|---|
| 1% | ~2% |
| 2% | ~5% |
| 4% | ~14% |
The takeaway from that table: 2% of Bitcoin is roughly as risky as holding one large tech stock, and doubling to 4% more than doubles the risk it adds. That’s why “just put 20% in, it’ll go up” is not investing — it’s concentrated speculation.
For a beginner, the practical rules to hold onto:
- Keep it to a slice you can lose entirely. Not “probably won’t lose” — could lose, and be fine. For most people that’s 1–5% of what they invest, not a meaningful chunk of their net worth.
- Size so a 70% drawdown wouldn’t force you to sell. If a 70% fall would wreck your finances or make you panic, the position is too big.
- Do not use money needed soon. Money for a house deposit, tuition, or an emergency fund has no business in Bitcoin. A full market cycle — roughly four years — is the minimum horizon serious investors talk about, and longer is better.
This is the single section that matters most, because it’s the one you control. You can’t control the price; you can control the size.
Should you buy in one lump sum or use dollar-cost averaging?
For a beginner, dollar-cost averaging (DCA) — a fixed dollar amount on a fixed schedule — beats trying to time the market, and it’s not close.
The mechanics are simple: instead of deciding “is today the right day to put $5,000 in?”, you put $100 every week (or $500 every month) regardless of price. When Bitcoin is down, the same dollar buys more; when it’s up, it buys less. Over time this lowers your average purchase price versus buying a lump sum at a random moment — and, more importantly, it removes the emotion that drives the buy-high, sell-low pattern.
Concretely, if you had a $1,000 budget, a sensible approach is to split it into five $200 buys over one to two months — or set up a recurring purchase and forget about it. The recurring version has a hidden benefit: you stop checking the price, which is where most beginner losses actually happen.
Lump-sum investing isn’t wrong — historically it has outperformed DCA when the market goes straight up — but it requires a conviction and a tolerance for an immediate drawdown that most beginners don’t have. DCA is the version of this decision you’re least likely to regret at 2 a.m.
Should you buy Bitcoin directly or through an ETF?
This is the decision most beginner guides skip, and it changes everything about custody and taxes.
| Buy directly on an exchange | Buy a spot Bitcoin ETF | |
|---|---|---|
| What you own | The actual bitcoin | Shares in a fund that holds bitcoin |
| Who holds the keys | You (or the exchange until you withdraw) | The fund’s custodian |
| Cost | Exchange trading fee, often ~0.1–0.6% per trade | Expense ratio ~0.25–0.40% per year |
| Tax wrapper | Taxable account only | Can sit in an IRA / retirement account |
| Main risk | You lose your keys, or the exchange fails | Counterparty and tracking risk, plus the fee |
| Best for | People who want self-custody and real coins | People who never want to manage keys |
Buying directly means creating an account on a major exchange, verifying your identity, and buying — then deciding whether to leave coins on the exchange or withdraw them to a wallet you control. Our step-by-step buying guide walks through it, and the Binance tutorial shows the exact screens.
💡 Don't have a Binance account yet? Sign up now — enter the referral code BN2688.
Buying an ETF means logging into the brokerage account you already have and buying a fund like BlackRock’s IBIT like any stock. There are no keys, no seed phrase, and nothing to back up — the fund’s custodian holds the Bitcoin. The cost is the annual expense ratio, and the trade-off is that you never actually hold Bitcoin directly, which purists will tell you defeats part of the point.
The honest heuristic: if the word “seed phrase” makes you nervous, the ETF is the lower-risk way to get Bitcoin exposure. If you want the full point of Bitcoin — holding an asset no institution can freeze or seize — buy direct and learn to self-custody properly. Neither is wrong; they’re different tools for different people.
How do you actually buy and store Bitcoin?
Once you’ve sized the position, the mechanics take minutes, and the storage decision is where beginners actually get hurt.
Buying: create an account on a large, regulated exchange (Binance and OKX are the two biggest), complete identity verification, deposit money by bank transfer or card, and buy. You can buy any dollar amount — one bitcoin divides into 100 million satoshis.
💡 Don't have an OKX account yet? Sign up now — enter the invite code 60895497.
Storing is the part that separates people who keep their Bitcoin from people who lose it. The rule of thumb, expanded in our storage guide: what you plan to trade can sit on the exchange; what you plan to hold for years belongs in a wallet you control — ideally a hardware wallet for meaningful amounts.
One first-hand detail most guides skip: the first time you withdraw from an exchange to your own wallet is genuinely nerve-wracking, because a wrong address means the money is simply gone. The standard practice — send a small test amount first, confirm it arrives, then send the rest — costs one extra network fee and has saved more Bitcoin than any hardware device ever will. Do it every time you use a new address.
The five-question checklist
Rather than a vague “it depends,” here’s a concrete filter. If you can answer yes to all five, a small Bitcoin position is a defensible choice. If you can’t, you have your answer.
- Is this money I could lose entirely and be fine? If losing 100% of it would change your life, the answer is no — regardless of what Bitcoin does next.
- Can I leave it untouched for four years or more? If you’ll need the money sooner, it doesn’t belong here.
- Will I still sleep if it drops 70%? If a 70% drawdown would make you panic-sell, either the position is too big or Bitcoin isn’t for you.
- Am I buying on a schedule, not on a headline? DCA yes, lump-sum-on-a-tweet no.
- Do I know how I’ll store it? Exchange, hardware wallet, or ETF — pick one before you buy, not after.
If you said yes to all five, the next step is to start small and boring: a fixed monthly amount you don’t feel, on an exchange or ETF you’ve researched. That is the entire strategy for most people, and it’s enough.
Common mistakes to avoid
- Panic-selling at the bottom. Every past drawdown has eventually been followed by new highs — but only for the people who didn’t sell. Selling at the bottom turns a paper loss into a real one.
- Buying too much at once, especially after a rally. Chasing a price that just surged usually means buying near a top. Small and steady beats big and dramatic.
- Using leverage. Borrowing to buy Bitcoin amplifies losses faster than it amplifies gains, and it’s the surest way to get wiped out in a dip.
- Leaving large amounts on an exchange. Exchanges are convenient and can fail. Meaningful holdings belong in self-custody — see hot wallet vs cold wallet.
- Following “guaranteed” tips. Anyone promising a return, a sure price, or “get in before it’s too late” is running the classic scam playbook, not giving advice.
- Investing before understanding. If you can’t explain in one sentence why you own it and how you’d lose it, you don’t own a position — you own a rumor.
The bottom line
Bitcoin can be a reasonable, high-risk, long-term addition to a beginner’s portfolio — provided it’s small (1–2%, per the research), bought on a schedule rather than on a hunch, held for years rather than weeks, and stored somewhere you understand. That’s the entire honest case, and it’s a conditional one: every upside has a matching drawdown, and no one can promise which comes next.
If you decide to proceed, do it in this order: understand what Bitcoin is if you’re new, pick a position size you could lose entirely, set up a recurring buy on a reputable exchange, and — before any serious money moves — learn how private keys and seed phrases work. The people who get hurt in crypto aren’t the ones who invested; they’re the ones who invested too much, too late, without understanding what they held. Stay on the other side of that line.
Don't have a Binance account yet?Sign up nowenter the referral codeBN2688
Frequently asked questions
Should I invest in Bitcoin right now?
How much of my portfolio should be in Bitcoin?
Is it better to buy Bitcoin directly or through an ETF?
Is $100 enough to start investing in Bitcoin?
Can I lose all my money in Bitcoin?
When is the best time to buy Bitcoin?
Editor-in-Chief & Lead Researcher
Editor of MyCryptoStart. Independent researcher of cryptocurrency exchanges, focused on fees, security, KYC, and onboarding — publishes step-by-step guides in plain English for beginners.
View author page →Some links on this page are affiliate links: we may earn a commission at no extra cost to you. This content is educational and is not financial, investment, or legal advice. Affiliate disclosure · Disclaimer.
Continue reading
What Is DeFi? Decentralized Finance Explained
DeFi is financial services — lending, trading, and earning — rebuilt on blockchains instead of banks. Learn how it works and the risks.
What Is Ethereum? Smart Contracts Explained
Ethereum is a decentralized computing platform powered by smart contracts. Learn how it works, what ETH and gas fees are, and how it differs from Bitcoin.
On-Chain Assets Explained: Tokens & NFTs
An on-chain asset is anything of value recorded on a blockchain — coins, tokens, and NFTs. Learn the three families and how to spot a real one.